Polymarket’s upgrade won’t automatically move existing bets to new contracts
Story summary
App users follow approval prompts, while integrations must keep CTF support and add V2 identifiers and permissions. The post Polymarket’s upgrade won’t automatically move existing bets to new contracts appeared first on CryptoSlate.
📌 Key Highlights & Takeaways
- App users follow approval prompts, while integrations must keep CTF support and add V2 identifiers and permissions.
- The post Polymarket’s upgrade won’t automatically move existing bets to new contracts appeared first on CryptoSlate.
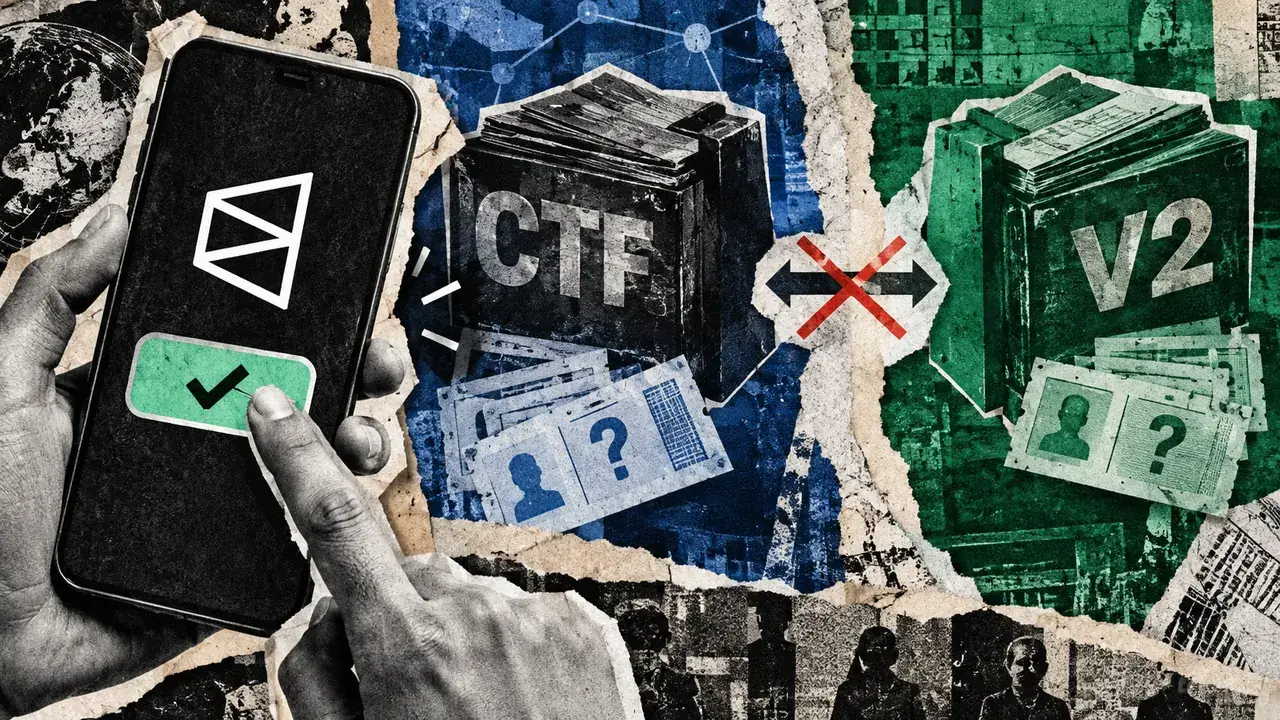
Polymarket’s Protocol V2 rollout does not automatically move existing bets held under its older Conditional Tokens Framework, or CTF, onto new contracts. Its migration guidance tells trading integrations to retain support for those holdings while adding a separate system for V2 positions and new trading permissions.
In his Oct. 5 announcement , Rajath Alex said Polymarket would run a few live test markets, known as canary markets, from Oct. 5 through Oct. 30. He described Nov. 2 as a tentative switch for newly created markets, rather than a deadline for converting every existing bet.
For people using Polymarket’s app or website, no technical migration is required. Users should complete any approval prompts shown in the app. The guides address Polygon-based onchain trading; Polymarket’s main documentation directs users of Polymarket US to separate documentation.
A separate mechanism does allow holders to move CTF positions into V2. Polymarket’s contract registry says the relevant condition or event must be registered by Polymarket first. Its indexing reference describes events connecting the old CTF balance to the new PositionManager balance. That is a distinct operation from updating trading software.
For developers, the change starts with where shares are recorded. Legacy CTF positions remain on the older ledger, while V2 balances sit in a separate contract called PositionManager. The contract migration guide requires integrations to handle the appropriate balances and retain CTF identifiers for older markets.
Permissions also stay separate. Under the API migration guide , the account holding a V2 buyer’s assets must authorize ExchangeV3, the new trading contract, to spend enough pUSD, Polymarket’s trading collateral, to cover purchases and fees. Selling requires permission for ExchangeV3 to operate on the seller’s PositionManager shares. Existing CTF permissions do not grant either approval.
Trading software must select the correct share identifier from each market’s version, even if both generations’ identifier fields appear in the response. V2 orders use position IDs and signing-domain version 3; CTF orders retain their exchange and signing-domain version 2. Those signing versions distinguish the two trading paths. Balance requests also distinguish V2 shares from CTF shares.
For integrations that create, combine or redeem positions directly through contracts, V2 uses Router. Creating positions requires approval for Router to spend pUSD; combining or redeeming them requires Router operator permission on PositionManager. Integrations also need to update balance handling and payout reads.
Crypto Profit & Yield Calculator
Simulate trading returns, staking APY, and crypto gains with real-time fee modeling.
Source: CryptoSlate.
Read the full story at the original source ↗
For questions: mrsmithcons@gmail.com.
❓ Frequently Asked Questions (Day Trading Hacks Briefing)
What on-chain catalyst or market signal triggered this Day Trading Hacks movement?
Institutional on-chain telemetry, cold storage accumulation, and derivative funding rates indicate spot liquidity positioning that underpins this Day Trading Hacks development.
How should investors interpret current liquidity pools and network hash activity?
Derivative funding remains balanced and exchange reserves continue trending downward, mitigating systemic liquidation cascades and strengthening the underlying structural floor.
Where are the critical technical support and invalidation levels?
Anchored volume-weighted average price (VWAP) benchmarks and high-density order book clusters near prior consolidation ranges serve as key risk management thresholds.
📈 Live Scalping Metrics & Prop Firm Risk Model
Institutional order flow data, risk-reward ratios, and prop challenge models.
⚡ Access Trading Terminal ➔More from 1UpTrade Live
 💎 Try2Rich
Industry Intelligence: Key Metrics, Syndicate Movements, and Emerging Catalysts in Digital Assets
Comprehensive 2026 editorial analysis exploring Digital Assets on Try2Rich. Discover key strategic frameworks,...
📈 FreeRich FIRE
FIRE Movement 2026: Inflation, Low Savings Rate Make Early Retirement Harder - News and Statistics
Breaking coverage reported by IndexBox: FIRE Movement 2026: Inflation, Low Savings Rate Make Early Retirement ...
 💵 GetRichFree Store
Apple Card $100 Signup Bonus
The Offer Direct Link to offer Apple Card is offering $100 bonus when you sign up for a new Apple Card and spe...
 🤖 1UpTrade Quant
Strategic Breakdown: Deep-Dive Analysis into AI Trading Bots and Global Market Dynamics
Comprehensive 2026 editorial analysis exploring AI Trading Bots on 1UpTrade Quant. Discover key strategic fram...